
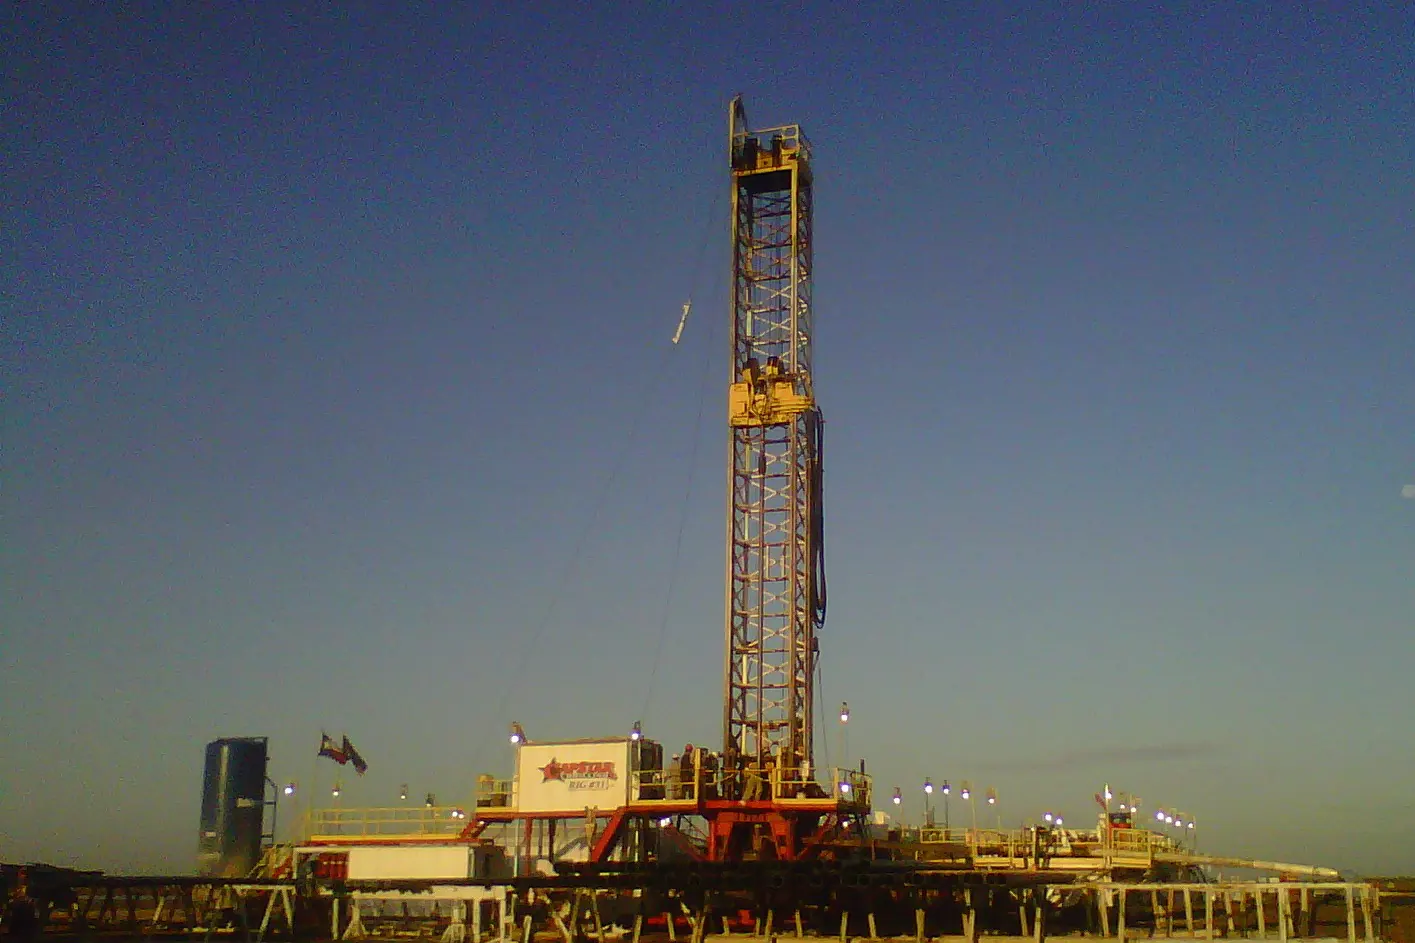
The United States produced an average of 12.9 million barrels per day of crude oil and condensate in 2023, according to the Energy Information Administration. That beat the previous US and global record of 12.3 million b/d, set by the United States in 2019, and it made the country the largest crude producer of any nation at any time for the sixth year running. By December 2023, monthly output had reached 13.3 million b/d.
What makes the record notable is how it was achieved. US drilling activity declined through 2023. Output rose anyway, because new wells were more productive. At the same time, exploration and production companies spent $234 billion on mergers and acquisitions, the most in real terms since 2012. These three facts, a production record, falling rig activity and a consolidation wave, are connected. Together they describe an industry that has learned to grow while spending less on drilling, and that is now reorganizing itself around a smaller number of very large operators.
Productivity, not activity
The EIA's analysis of the December figures is direct: production records have come despite declining drilling activity, because operators are getting more oil out of each new well. Since first surpassing the 2019 record in August 2023, output rose another 2%, ending the year 0.3 million b/d above the November 2019 peak.
There are several sources of that productivity. Longer laterals expose more rock to each well. Improvements in completion design, including more sand and better spacing, raise initial production. Drilling rigs themselves move faster between locations and drill more feet per day. Pad drilling allows several wells to be drilled from a single site, cutting setup time.
The important implication is that the rig count is a weaker guide to future production than it used to be. Analysts who saw rig numbers falling in 2023 and expected production to follow were wrong. A smaller fleet of more capable rigs, run by operators focused on their best acreage, produced more oil.
Why no one else is close
The EIA notes that no other country has reached production capacity of 13.0 million b/d. Saudi Aramco recently scrapped plans to raise its maximum sustainable capacity to that level by 2027. The United States, Russia and Saudi Arabia together accounted for 40% of global oil production in 2023, about 32.8 million b/d, and these three have been the top producers since 1971.
The difference is in how output is controlled. Saudi and Russian production is managed through state decisions and OPEC+ agreements. In 2023 both were deliberately holding output below capacity to support prices. US production is the sum of decisions by many companies responding to prices, costs and investor expectations. The record therefore reflects market economics, not policy. It also means US output does not respond to calls from Washington to produce more or less, at least not quickly.
The consolidation wave
The $234 billion spent on deals in 2023 was dominated by corporate mergers, which made up 82% of the total. Two transactions accounted for a large share: ExxonMobil's announced acquisition of Pioneer Natural Resources for $64.5 billion, and Chevron's announced acquisition of Hess. The EIA describes the dealmaking as a return to the longer-term trend of consolidation after transactions fell during the price volatility of 2020 and 2022.
For production, consolidation cuts both ways.
On one side, larger operators with contiguous acreage can drill longer laterals, share infrastructure and plan development across many years. The productivity gains that delivered the 2023 record are easier to capture at scale. A major that buys a large Permian position can develop it more efficiently than several smaller owners with fragmented leases.
On the other side, large public companies have made capital discipline a central promise to shareholders. They are less likely than smaller independents to raise drilling sharply when prices rise. That reduces the price responsiveness of US supply. In the shale boom of the early 2010s, higher prices quickly brought more rigs. In a consolidated industry, the response is slower and smaller, because the same companies control more of the drilling program and plan it around returns rather than volume.
What this means for prices and for OPEC+
A more productive but less responsive US industry is a different competitor for OPEC+. When US output reacted quickly to price, any OPEC+ cut risked being offset by American growth within a year. If US growth now comes mainly from productivity, with drilling held roughly steady, the offset is still there, but it is slower and steadier.
That helps explain why OPEC+ has been willing to maintain voluntary cuts. The group can hold back barrels without seeing them replaced quickly by a surge in US drilling. Steady US growth still erodes the group's market share over time, but it does not punish every cut immediately.
For consumers, a slower supply response means price spikes may last longer. In 2022, high prices did not produce a rapid increase in US drilling of the kind seen a decade earlier. That pattern seems likely to persist.
The limits of productivity
Productivity gains are not unlimited. The best acreage is drilled first. As operators move to less productive locations, each new well may yield less. Some of the gains from longer laterals and denser completions may also accelerate the decline of nearby wells, so that higher initial output comes partly at the expense of later production.
Consolidation could extend the runway. Large operators with deep inventories can schedule drilling to manage depletion, and they have the engineering resources to keep improving techniques. But it could also slow growth if acquirers choose to prioritize cash returns over expansion. Investors in large oil companies have consistently rewarded dividends and buybacks over production growth since 2020.
A record with an unusual shape
The 2023 record is real and significant. It rests on productivity rather than on a drilling boom, which makes it more durable in the short term but more dependent on continued technical progress in the long term. The merger wave consolidates that productivity in the hands of a few large companies whose priorities are returns, not volume.
For energy security, that is a reasonable outcome. The United States can sustain high production at moderate prices without the boom-and-bust cycles of the past. For anyone hoping that American output will rise sharply to offset future supply shocks, the record should be read with some caution. The industry that delivered it is built to be steady, not to surge.