
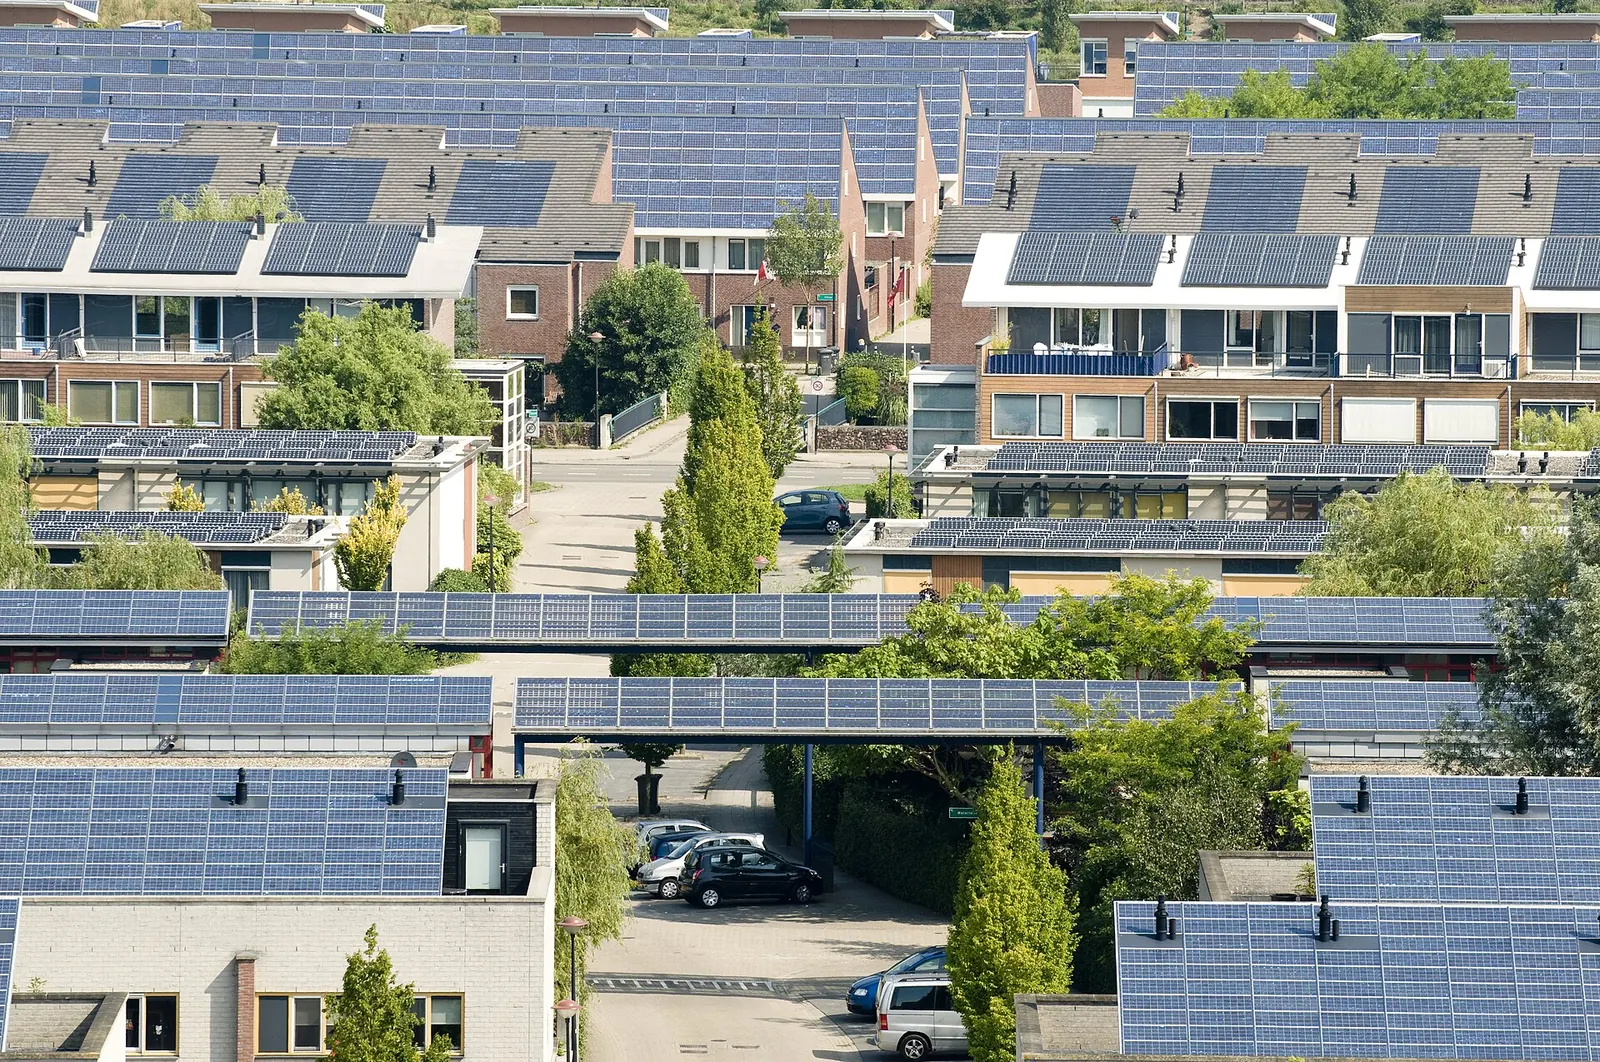
European electricity markets in 2024 are delivering a clearer decarbonisation signal than many critics expected after the 2022 price crisis, while simultaneously exposing the next binding constraint: flexibility. The European Commission's quarterly market reporting, completed for the full year in March 2025, would show renewables reaching 47% of the EU power mix in 2024, with renewable generation up 93 TWh. Solar rose 19% (+38 TWh). Hydropower rose 13% (+43 TWh). Additional installed renewable capacities of 59 GW supported output. Fossil generation dropped 10%, with coal-fired generation down 27% (-54 TWh) and gas generation down 25% (-30 TWh). The European Power Benchmark averaged 74 euros per MWh in 2024, 22% lower year-on-year. Retail household prices in EU capital cities were down 7% to 242 euros per MWh.
In mid-September 2024, that full-year scorecard was still being written, but the summer pattern was already plain. April 2024 had seen renewables hit a 54% share of generation, a historical high for the month, supported by solar and hydro. Lower gas prices in the first half of the year and moderated demand helped wholesale power retreat from crisis levels. Negative prices became more common in high-solar hours, a sign of success in deployment and of stress in a system short of storage and demand response.
Eurelectric's later Power Barometer would put the EU average wholesale path as 227 euros per MWh in 2022, 97 in 2023, and 82 in 2024, and would warn that flexibility resources rose only marginally while renewables surged. Negative prices occurred on average 4.5% of the time in 2024. Gas still sets prices at the margin in many hours, which is why TTF and power remain coupled. Industrial demand remains below pre-crisis norms in several sectors. Distribution grids are the quiet bottleneck for electrification. Making the transition add up means aligning retail design, network charges and industrial electrification support so that cleaner power becomes a locational advantage rather than a stranded cost.
Market participants should also keep an eye on inventory quality, not only inventory quantity. Contango and backwardation, floating storage economics, and the location of stocks relative to demand centres determine whether a headline surplus is actually available to distressed buyers in a given week. The same discipline applies to gas storage fill percentages, coal port stocks, and mineral warehouse receipts. Headline ratios without location and quality context are how desks get blindsided.
Cross-checks against multiple agencies remain essential. Producer organisations, consumer agencies, shipping analytics firms and regulators often describe the same physical system with different residual assumptions. The professional response is triangulation, not allegiance to a single dashboard. Where numbers in this piece appear, they are taken from pages that were opened and are listed at the end of the article.
For emerging-market importers, bill management is energy security. Hedging, storage, demand efficiency and fuel-switching options reduce the welfare cost of global shocks. For exporters, credibility of contract delivery and of production policy is a commercial asset. For transit states, corridor stability is fiscal and geopolitical capital. Each role implies different investments; all of them imply honesty about physical constraints.
The Transition Economics Institute tagline, Making the transition add up, is used here as an engineering standard rather than a slogan. Addition means connecting megawatts to molecules, molecules to voyage days, voyage days to bills, and bills to political tolerance. It also means connecting climate targets to mineral tonnes and grid lead times. Articles that celebrate only one side of that arithmetic are incomplete.
Second-order couplings deserve routine attention: power prices feeding industrial gas demand; Chinese LNG swings releasing or absorbing Atlantic cargoes; coal import cycles altering dry-bulk freight; mineral export controls raising equipment costs for the renewables that cut fossil demand. Systems thinking is the minimum professional standard for energy policy advice in this decade. Scenario tables should show joint tails, not only single-factor shocks, because regional politics can move oil, gas freight and mineral logistics together.
Risk communication to non-specialist audiences should separate three layers: the physical flow change, the price transmission channel, and the policy response option. Mixing those layers produces either panic or complacency. Physical barrels can still arrive while prices spike on freight and risk premia. Prices can fall while security margins thin. Policy can spend money on the wrong buffer. Clear layering keeps cabinet discussions usable.
Data hygiene is part of engineering culture. Report units. Name the year. Distinguish thermal from metallurgical coal, spot from contracted LNG, crude from products, mined ore from refined metal. Conflations that sound fluent in conversation become errors in investment memos. The authors of this series treat that hygiene as non-negotiable.
Governance timelines should be mapped beside price charts on the same page. A ministry that watches only the front-month contract will miss the compliance meeting, the storage mandate deadline, the interconnection outage, and the mineral licensing decision that actually move the medium-term balance. Equally, a ministry that watches only targets without landed-cost feedback will design politically brittle pathways. The craft is to keep both views active in the same weekly pack.
Seasonality still disciplines the calendar. Winter gas and power stress tests differ from summer peak-cooling tests. Refinery maintenance seasons change product balances. Monsoon logistics affect coal discharge in South Asia. Harvest and industrial cycles shift diesel. A global energy note that ignores the clock will mis-order its warnings. The authors therefore date each piece not as decoration but as a positioning statement inside the seasonal and institutional year.